FATF Vice-President Vivek Aggarwal has urged the fintech industry to increase investments to combat emerging threats from AI, scam compounds, virtual digital assets, and quantum computing. He warned that these technological challenges pose a significant risk to India's rapid growth in the fintech sector, highlighting a current lack of adequate investment and risk realisation within the industry.
The Government of Karnataka has called for enhanced collaboration with the BFSI and FinTech sectors to bolster its technology ecosystem and accelerate the adoption of innovative solutions. This initiative, discussed at an Industry Meet, aims to foster partnerships between government, industry, and academia, particularly through programmes like 'Government First', in preparation for the Bengaluru Tech Summit 2026.
'So, we would work with our members to ensure that we as an SRO create some sort of due diligence for fintechs.'

'There has to be a safe harbour for licensed entities, which have followed all the norms prescribed by the RBI.'
Indian banks and non-banking financial companies (NBFCs) are undertaking a comprehensive review and reset of their engagement terms with fintech firms, driven by the Reserve Bank of India's (RBI) draft Guidance on Regulatory Expectations for Data Governance and the stringent compliance requirements of the Digital Personal Data Protection (DPDP) Act, 2023, and its 2025 Rules.
Prime Minister Narendra Modi has called upon the fintech industry to expand the global footprint of the Unified Payments Interface (UPI), advocating for its integration with international payment systems to reduce remittance costs for the Indian diaspora. Speaking at the Global Fintech Fest, Modi highlighted UPI's current presence in 11 countries and its connection with Singapore's local system, urging further expansion into nations with significant Indian populations or trade ties. He also stressed the need for India to set its own global payment standards and for the fintech sector to innovate beyond payments, focusing on cybersecurity, ethical data protection, and regulatory frameworks.
Indian fintechs and associated entities are hoping that the Union Budget 2024 will provide a boost and empower firms to extend their reach beyond Tier-II regions, with an emphasis on supporting enterprises led by women. The fintech industry, which has witnessed regulatory reforms over the last year, expects the Budget, scheduled to be presented by Finance Minister Nirmala Sitharaman on February 1, will further encourage financial inclusion, empower micro-small-medium enterprises (MSMEs) with lending solutions, and push for upskilling initiatives for the country's young workforce.

Prime Minister Narendra Modi has urged the fintech sector to expand the global reach of India's Unified Payments Interface (UPI), connecting it with local systems in other countries to help the diaspora save on remittance costs.
ICICI Bank is seeking recoveries of at least 100 crore from fintech firms, alleging merchant misclassification of their business, a practice that has eroded the bank's interchange income. The dispute, lodged with global card network Visa, highlights growing discomfort among banks and intensified scrutiny from the Reserve Bank of India.
Commerce Secretary Rajesh Agarwal highlighted the critical need for India to diversify its services exports beyond the dominant IT/ITeS and professional services sectors. Speaking at the Global Fintech Fest 2026, he emphasised the vast potential in the global financial services market, where India currently holds a small share, and stressed how fintech solutions, like UPI, can drive growth, reduce remittance costs, and support MSME trade finance, ultimately leading to sustainable economic expansion.

Chief Economic Advisor V Anantha Nageswaran has stressed the urgent need for India's financial sector to proactively address the safety and security risks of artificial intelligence, stating that waiting for problems to materialise is not an option.

'While salary increments are moderating compared to last year, not all functions are moving at the same pace.'
Fintech firm BharatPe has publicly supported the government's new Merchant Discount Rate (MDR) framework for UPI merchant transactions, which introduces a 0.4% fee on transfers over Rs 2,000. The company has also distanced itself from its former co-founder Ashneer Grover's strong criticism of these changes, stating his remarks are personal and do not reflect BharatPe's official position. BharatPe believes the new framework will strengthen digital payment economics while protecting consumers and small merchants.
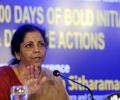
Finance Minister Nirmala Sitharaman has called for enhanced accountability and safeguards for artificial intelligence, particularly as it integrates into critical sectors like finance. Speaking at the Global Fintech Fest, she highlighted the dual nature of AI, capable of accelerating transactions but also amplifying fraud and cyberattacks. Sitharaman stressed the need for human and institutional responsibility in AI-driven decisions, urging regulators and companies to scrutinise high-risk AI applications. She also proposed a federated industry platform for Indian tech companies to navigate international regulations and ensure tax compliance globally.
The National Payments Corporation of India (NPCI) stated that the Merchant Discount Rate (MDR) "is distributed only amongst the UPI ecosystem, to further invest into infrastructure resilience, innovation, cybersecurity (protecting the UPI infrastructure with banks and non-banks) and customer service."

The government is introducing a 0.4% Merchant Discount Rate (MDR) on UPI person-to-merchant payments above Rs 2,000, effective October 15. This move ends the zero-MDR regime, aiming to fund UPI infrastructure and sustainability, as the previous government subsidy was insufficient to cover operational costs. Payments between individuals and most everyday merchant transactions will remain free.
Fintech company BharatPe has expressed strong support for the government's new Merchant Discount Rate (MDR) framework for UPI merchant transactions, which introduces a 0.4% fee on transfers exceeding Rs 2,000. The company explicitly distanced itself from critical remarks made by its former co-founder Ashneer Grover, clarifying that his views do not represent BharatPe's stance. BharatPe CEO Nalin Negi highlighted that the framework aims to strengthen digital payment economics, protect consumers and small merchants, and expand adoption in underserved markets, with most transactions remaining unaffected.

Finance Minister Nirmala Sitharaman has urged the Reserve Bank of India to accelerate its central bank digital currency initiatives, emphasising the need to sharpen capabilities with the digital rupee amidst rapid advancements in tokenisation, agentic AI, and quantum computing. She also highlighted critical concerns regarding cybersecurity, warning that autonomous AI systems are evolving rapidly and require robust safeguards. Sitharaman proposed a federated industry platform to give India's technology ecosystem a collective international voice.
EPF wage ceiling rising to Rs 25,000 could increase employer statutory contributions by Rs 1,200 monthly per employee.

The United Arab Emirates (UAE) has expressed intent to invest an additional $25 billion in India, with an ultimate goal of reaching $100 billion in investments, Union Minister Piyush Goyal announced. This comes as both nations plan to enhance cooperation in shipping, ports, energy, and emerging technologies, against a backdrop of expanding bilateral trade.

Finance Minister Nirmala Sitharaman announced that the Goods and Services Tax (GST) Council's October 7 meeting will focus on 'GST 2.0' process reforms, including e-invoicing and input tax credit rules, while also addressing complex issues surrounding the taxation of the digital economy and cryptocurrency.

State Bank of India Chairman C S Setty stated that banks will take three to four months to deploy the significant funds mobilised through foreign currency non-resident (bank), or FCNR(B), deposits, which is unlikely to cause "abnormal lending". He also highlighted the need for agentic artificial intelligence (AI) costs to fall sharply for its widespread deployment in India, envisioning its role in transforming banking from fraud detection to personalised financial assistance.
India's MSME sector faces a significant formal credit gap of approximately Rs 60 lakh crore, with traditional channels meeting only a fraction of the demand. A new report suggests that a centralised, interoperable digital layer could effectively bridge this gap and enhance productivity across the formal business sector by digitising workflows and enabling cash-flow-based underwriting.

Axis Bank MD & CEO Amitabh Chaudhry has cautioned that the surge in FCNR(B) deposits could lead to 'abnormal lending' as banks seek to deploy excess liquidity, while also hinting at a potential interest rate hike in the near future.

The Indian government has introduced a 0.4% Merchant Discount Rate (MDR) on UPI person-to-merchant (P2M) transactions exceeding Rs 2,000, effective October 15. This move ends nearly six years of fully free UPI payments, though person-to-person (P2P) transfers and small P2M payments remain free. The charges aim to bolster investment in UPI infrastructure, with specific exemptions and caps for essential sectors.

India's UPI International payment system is now playing a crucial role in humanitarian efforts, enabling seamless disaster relief donations from Indian users to Nepal's Prime Minister Disaster Relief Fund, showcasing its growing global acceptance and utility beyond tourism. UPI IMAGE: Kindly note that this image has been posted for representational purposes only. Photograph: Unsplash Key Points UPI International, initially for Indian tourists, is now facilitating disaster relief donations to Nepal's Prime Minister Disaster Relief Fund. The embassy of Nepal in India is actively encouraging Indian users to utilise their UPI apps for these contributions. This marks a significant shift, expanding UPI's cross-border use case beyond tourism to include inbound collection for foreign governments. The move positions UPI International alongside global payment giants like Alipay+ and UnionPay for international aid. Donors need to activate the UPI International feature on their apps to transact, with amounts converted from INR to NPR.

For India, the goal is not simply to host another grand diplomatic gathering. It is to prove that a diverse coalition of emerging powers can still deliver.

Making UPI payments fee-based for some transactions could enhance mental reservations against digital payments -- which have largely been overcome -- once more. Do we want to regress?, asks R Jagannthan.

Bank fraud is no longer just an external cyber threat -- insiders with legitimate access can exploit banking systems, trusted credentials and institutional blind spots to quietly siphon money.
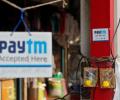
One 97 Communications Ltd, operating Paytm, is set to issue its first bonus shares, following a landmark year of achieving its maiden full-year profit and gaining significant market share. The board will meet on July 20 to decide on the bonus issue, reflecting confidence in its financial strength and aiming to improve stock accessibility for retail investors.

The biggest challenge to widespread deployment is no longer AI. It is the financial and commerce infrastructure that was built decades ago for deterministic software and human interactions -- not autonomous AI agents.
Corporate India is projected to offer salary increments ranging from 8.6 per cent to 10.2 per cent across various industries in the financial year 2026-27, primarily fuelled by a sustained demand for skilled and execution-focused talent, according to a TeamLease Services report.
Investors and startup executives are calling for extending the period for an entity to be recognised as a startup from 10 to 15 years for deep-tech companies.
Indian companies' overseas expansion plans are holding strong despite geopolitical tensions in West Asia, driven by structural factors like supply-chain diversification, free trade agreements, and market expansion, according to Ajay Sharma, managing director and head of banking at HSBC India.

Following the Reserve Bank of India's (RBI's) action against Paytm Payments Bank, participants in the fintech ecosystem have turned their attention to giving priority to compliance with regulatory norms. Fintech industry players say the episode will ensure adherence to such measures. Executives Business Standard spoke to said companies should have clarity on their requirements.
This would imply a 29 per cent year-on-year rise, significantly lower than growth rates seen in recent years.
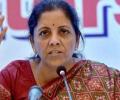
Finance Minister Nirmala Sitharaman met with bank heads to discuss the risks associated with Artificial Intelligence (AI) following global concerns about Anthropic's Mythos model and its potential threat to financial systems' data security.

'...A new challenge has emerged in the form of Mythos.'

'I don't see fear becoming a dominant factor for retail investors.'

A potential US-Iran peace deal, expected to be signed on June 19, is anticipated to ease geopolitical stress and benefit various sectors, particularly in India, with analysts suggesting investors await finer details before making significant moves.
